Gisela Hoffmann · 24 October 2026
Constraints in Virgin Gold Availability Drive Expansion of Secondary Precious Metals Trading Platforms
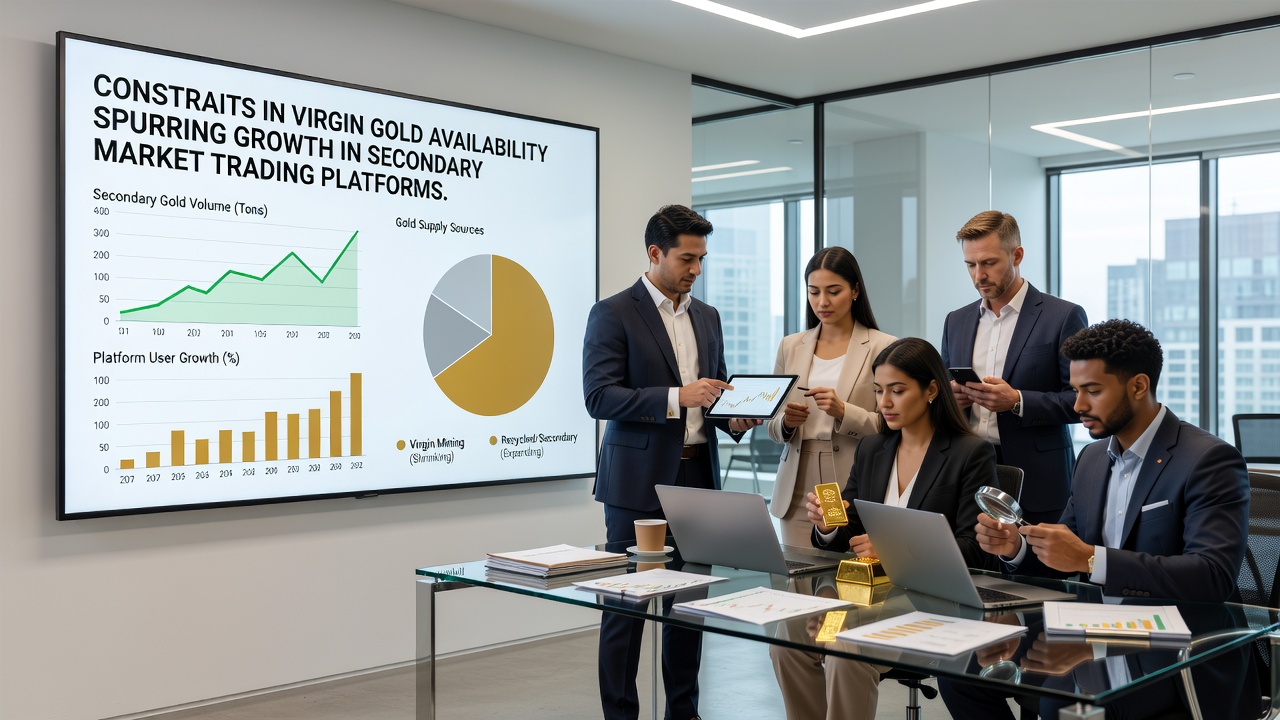
Virgin gold production faces mounting pressure from depleting ore grades at major mines, extended permitting timelines, and stricter environmental standards across key producing regions, and these factors have accelerated interest in secondary market platforms that facilitate trading of recycled and previously refined precious metals. Data released in October 2026 indicated that global mine output had fallen below 3,000 tonnes annually for the third consecutive year, according to figures compiled by the United States Geological Survey, while volumes handled through secondary trading venues showed consistent double-digit percentage growth in the same period.
Shifts in Primary Supply Patterns
Researchers tracking production trends note that established gold districts in Australia, Canada, and South Africa continue to report lower extraction rates because remaining reserves sit at greater depths or contain lower concentrations of recoverable metal, and this situation has prompted mining companies to prioritize cost controls over volume expansion. Those who monitor exploration budgets observe that new project approvals have slowed in several jurisdictions, partly due to requirements for extensive baseline environmental studies and community consultations that extend project timelines by several years on average. Figures from Natural Resources Canada reveal that the country's gold mine production declined by roughly 8 percent between 2023 and 2025, a drop attributed to both operational challenges at mature sites and regulatory reviews that delayed restarts at previously idled properties.
Regulatory Pressures on New Mining
Policy changes in multiple countries have added layers of oversight for new and expanding mines, including mandatory biodiversity offsets and stricter water management rules that increase capital costs for operators. Observers note that the European Union's updated mining directives, implemented in phases through 2025, require companies to demonstrate net-positive environmental outcomes before permits are granted, and similar frameworks have appeared in parts of Latin America and Southeast Asia. These requirements have lengthened the interval between discovery and first production, which in turn reduces the near-term pipeline of newly refined gold entering global markets. Industry reports compiled by the World Gold Council highlight that the average time from resource definition to commercial output now exceeds fifteen years in many jurisdictions, up from roughly ten years two decades earlier.
Secondary Market Platforms Respond
Trading platforms focused on secondary precious metals have expanded their offerings to include verified recycled gold, industrial scrap, and jewelry feedstock, and these venues provide transparent pricing mechanisms that connect suppliers of used material with refiners and fabricators. Growth in this segment reflects both the constrained primary supply and rising demand from electronics manufacturers and jewelry producers who seek traceable sources that carry lower regulatory risk. Data compiled by exchanges operating in Singapore and Toronto show that secondary gold contracts increased by more than 25 percent in the twelve months ending September 2026, while spot volumes for newly mined bars remained relatively flat over the same interval.
Technology and Verification Advances
Platform operators have invested in blockchain-based tracking systems and third-party assay partnerships that allow buyers to confirm the provenance and purity of secondary lots before settlement, and these tools have reduced transaction friction that once limited participation from smaller refiners and manufacturers. Studies published by academic researchers at the University of British Columbia indicate that digital verification reduces the time required for material acceptance from weeks to days in many cases, thereby improving liquidity for recycled feedstock. As a result, more participants now route material through organized platforms rather than bilateral deals that lack standardized documentation.
Regional Variations in Secondary Trading
Activity levels differ by geography because local regulations and collection infrastructure influence how much gold becomes available for reprocessing, yet the overall pattern shows secondary volumes rising in markets where primary supply constraints are most pronounced. In the United States, for example, scrap recovery programs tied to electronics recycling have supplied increasing quantities to refiners, while in parts of Europe collection networks for end-of-life jewelry and industrial components have matured under extended producer responsibility rules. Participants in these regions report that organized trading venues offer clearer price discovery and settlement terms than traditional dealer networks, which supports higher throughput even when total physical supply remains stable.
Outlook for Market Participants
Those who follow precious metals logistics note that secondary platforms continue to develop specialized contracts for different purity grades and lot sizes, and these products allow refiners to match feedstock more precisely with downstream fabrication needs. Continued investment in assay automation and logistics integration is expected to further lower barriers for smaller suppliers, while primary production remains subject to the same geological and regulatory factors that have limited growth in recent years. The interplay between these supply channels continues to shape how gold and other precious metals move through global markets.
Conclusion
Constraints on virgin gold availability have coincided with measurable expansion in secondary trading platforms, and data from multiple regions document higher volumes handled through organized venues that emphasize traceability and efficient settlement. The combination of declining mine output, extended project timelines, and regulatory requirements has created conditions in which recycled material plays a larger role in meeting demand from fabricators and investors alike. As verification technologies mature and collection systems expand, the infrastructure supporting secondary markets appears positioned to handle additional throughput in the years ahead.